Impact of Banks on the Economy

Katrina Brindle writes:   On the morning of September 15 2008, the Lehman Brothers declared bankruptcy, introducing a chain of events that would throw Wall Street and the global market into a state of crisis and economic paralysis. Delegates assuming the roles of key figures in both the private and public sectors of the US economy were introduced to this crisis during the second “Too Big to Fail” committee meeting at McMUN. While certain ideological divisions between representatives for the federal government and CEOs of financial juggernauts within the committee were to be expected, the cleavages found within this crisis extended much further than the domestic squabble about who would be truly to blame for such systemic financial failures.

CEO of Goldman Sachs Lloyd Blankfein proposed a directive emphasizing the importance of reaching out to foreign markets to help mitigate this meltdown. He insisted that there is no use for a “fatalist attitude” when facing this kind of adversity. Unfortunately, this commitment to reject any pessimistic or reactionary stance did not sit well with France’s foreign policy, and the country decided to freeze all US trading assets as an expressly punitive action. What France’s Minister of Finance Christine Lagarde demanded from the committee was to act in ways which would restore confidence and trust in the American economy, a demand that was echoed by an American public on the precipice of a recession and devastating financial loss.

The 2008 crisis was not only one of financial turmoil, but one that spoke directly to the psychological ramifications of having the “American Dream” ripped out of the foundation of a country built on the pillars of prosperity and a successful free market economy. Stabilizing banks could be done through federal bailouts and foreign investment, but how could one influence a country’s public perception in any meaningful way during a time of such urgency? After the stunning announcement from the French Minister of Finance, the committee stayed true to its goals of overcoming political differences and passed five different directives by the end of the session, one of which directly targeted public perception of the crisis. “Keep Confidence High”, proposed by Lloyd Blankfein, Ken Lewis and Ron Logue, suggested that the federal government should lower interest rates to 2%, in order to increase liquidity and bail out mid-market troubled banks, but most importantly encouraged an increased transparency in the government handling of this market failure, through public announcements and updates.

As the market failure unfolds and the problems that are given to the delegates will exponentially grow in complexity, the issue of assigning guilt and culpability will become increasingly less relevant. In order to survive this simulation, the delegates cannot simply formulate policies that satisfy the demands of foreign finance ministers. They will have to answer to the fears and insecurities of the American public, the body that has the most to lose in the blame game of Wall Street.
Tentacles of the Big Banks


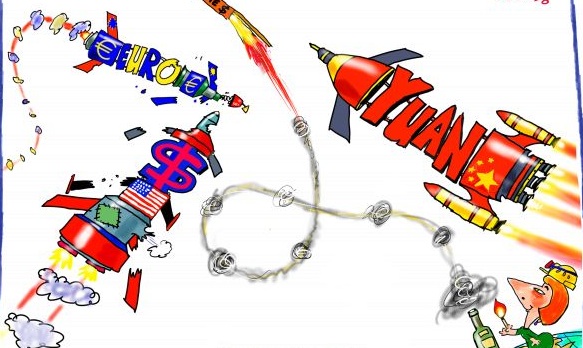
China and the Exchange Rate

China has no intention of devaluing its currency to push up exports nor any plans to enter into a currency war, Premier Li Keqiang assured the managing director of the International Monetary Fund, or IMF, Christine Lagarde, in a telephone conversation.

Addressing concerns over the depreciation of the Chinese currency, Li reiterated there is no basis for a continued devaluation of the yuan and denied China was reducing the value of its currency to boost weakening exports.

China exercises tight control over the renminbi exchange rate, setting a daily reference rate, and only allowing for a maximum fluctuation of 2 percent.

Some analysts interpret yuan devaluation as an attempt by the country to boost its slowing economy, while Beijing argues it is a way to gauge its currency against the dollar.

Li also assured Lagarde, China will increase communication with the market to “keep the RMB exchange rate basically stable at an adaptive and equilibrium level” and requested the IMF head to repose confidence in the Chinese economy despite the slowdown.

Li said China was capable of maintaining stable and sustainable growth, a week after it was revealed the Asian giant’s GDP grew 6.9 percent in 2015, its lowest ever in 25 years.

The discussion between Li and Lagarde comes shortly after the IMF’s quota reforms – that gives greater say to emerging economies including China – take effect, and at a time when Lagarde is looking for support to renew her tenure as head of the financial institution.

However, it is unknown if the Chinese premier offered to endorse Lagarde, who has already received backing from several European governments, as also from Japan and Brazil.

Yuan and Dollar

Warren Asks: Is Justice Rigged?

Senator Elizabeth warren finds punishments meted out to financial industry shockingly weak.

Democratic U.S. Senator Elizabeth Warren released on Friday a report criticizing what she called “shockingly weak” punishments for corporate crimes and condemned the Justice Department and Securities and Exchange Commission for their lax approach.

Warren, in a 13-page report titled “Rigged Justice,” outlined 20 civil and criminal cases from 2015 that she said illustrated patterns of weak and problematic enforcement of white-collar crimes, either as a result of “limited resources or lack of political will.”

“The Obama administration has made repeated promises to strengthen enforcement and hold corporate criminals accountable, and the DOJ announced in September that it would place greater emphasis on charging individuals responsible for corporate crimes,” Warren wrote.

“Nonetheless … accountability for corporate crimes is shockingly weak.”

Warren, a favorite among progressives, criticized the Justice Department and federal law enforcement agencies for rarely prosecuting individuals.

She called the SEC “particularly feeble” and said loose regulation at other agencies often turns legal rules into suggestions, which companies can freely ignore.

Warren said federal law is unambiguous in stating that if a corporation has committed a violation, individuals working there also must be at fault, but that federal agencies rarely pursue convictions of large corporations or their executives.

“If justice means a prison sentence for a teenager who steals a car but it means nothing more than a sideways glance at a CEO who quietly engineers the theft of billions of dollars, then the promise of equal justice under the law has turned into a lie,” she wrote.

“The contrast between the treatment of highly paid executives and everyone else couldn’t be sharper.”

The report, which Warren said will be the first in an annual series on enforcement, described low-punishment cases ranging from for-profit colleges engaging in deceptive recruitment practices to General Motors covering up years of ignition switch problems in its vehicles.

Another example listed was the Upper Big Branch Mine Disaster, in which Massey Energy CEO Donald Blankenship was convicted of one misdemeanor following a mine explosion that killed 29 people, despite his company’s history of safety failures.

Jail Offending Bankers


Who’s Who in Corruption

Denmark may not have a lot in common with North Korea and Somalia but all three nations placed first in their respective categories on the 2015 Corruption Perceptions Index released Wednesday by Transparency International, a Berlin-based organization that tracks perceived levels of public sector fraud and dishonesty worldwide.

For the second year running Denmark, the index showed, is the country with especially “high levels of press freedom; access to budget information so the public knows where money comes from and how it is spent; high levels of integrity among people in power; and judiciaries that don’t differentiate between rich and poor, and that are truly independent from other parts of government.”

North Korea and Somalia, were the joint-worst performers. The United States came 16th out of 167 nations, its best ever showing since the survey began in 1995.

Not a single country in the world is corruption-free, according to the survey, and some 68% of nations have what Transparency International calls a “serious problem with corruption,” meaning the high-level abuse of power that benefits the few at the expense of the many is especially pronounced in more than two-thirds of countries worldwide.

Here are the top 10 nations perceived to be the least corrupt:

  • Denmark
  • Finland
  • Sweden
  • New Zealand
  • Netherlands
  • Norway
  • Switzerland
  • Singapore
  • Canada
  • Germany

And the top 10 worst-performing countries:

  • North Korea/Somalia
  • Afghanistan
  • Sudan
  • South Sudan
  • Angola
  • Libya
  • Iraq
  • Venezuela
  • Guinea-Bissau
  • Haiti

Corruption in Spain

Lagarde: Ending Inequality is the Key to a Healthy Global Economy

The overall mood was described by many as “gloomy” at the World Economic Forum. Others were “cautiously optimistic.” Discussions focused on whether China’s transition to a new growth model will continue to unsettle markets, whether the flow of refugees will fracture Europe’s unity, whether robots will replace people and jobs, and whether the global economy can start to fire on all cylinders to produce more sustainable and inclusive growth.

The road ahead is going to be bumpy, these transitions can be broadly helpful to the global economy — provided they are well managed and that countries implement smart policies.

The International Monetary Fund are supporting our 188 member nations in that effort. We do this through our core activities — lending, policy advice, and technical assistance — as well as by helping to deal with a set of emerging issues that are of increasing importance to them: female empowerment, energy and climate change, and reducing excessive inequality.

These issues are what we call “macro-critical” — essential to boost growth that is both durable and inclusive.

Christine Lagarde speaks out for equaity:

Take inequality, for example. The traditional argument has been that income inequality is a necessary by-product of growth, that redistributive policies to mitigate excessive inequality hinder growth, or that inequality will solve itself if you sustain growth at any cost.

Based upon world-wide research, the IMF has challenged these notions. In fact, we have found that countries that have managed to reduce excessive inequality have enjoyed both faster and more sustainable growth. In addition, our research shows that when redistributive policies have been well designed and implemented, there has been little adverse effect on growth.

Indeed, low growth and high inequality are two sides of the same coin: Economic policies need to pay attention to both prosperity and equity.

Increasing women’s economic participation in the labor market is another potentially game-changing contributor to greater and more equitable growth. In reviewing 143 countries, we found that almost 90 percent of them have at least one important legal restriction that makes it difficult for women to work.

Moreover, women face a double disadvantage in the job market: They are less likely to have a paid job than men and, if they get a job, they will earn significantly less than their male colleagues — even with the same level of education and in the same occupation.

Eliminating these employment gender gaps could boost GDP significantly — for instance, by 5 percent in the United States, 9 percent in Japan, and 27 percent in India. The potential to spur growth and reduce inequality also applies to the environment and energy policies. Like many others, I was encouraged when the world leaders signed the global climate agreement in Paris last December. But this is only the beginning. Signed agreements now need to be implemented.

Again, IMF research has indicated that carbon pricing could be transformative, both in freeing up additional resources for investments in health and education and in helping to preserve the planet.

These issues are key to a better global economy that benefits everyone. But there is no silver bullet. The drivers of inequality — of opportunity as well as outcome — vary across countries, and there is no one-policy-fits-all solution.

What is crystal clear, however, is that excessive inequality is a burning issue in most parts of the world, and that too many poor and middle-class households increasingly feel that the current odds are stacked against them. The overriding challenge facing policy makers in 2016 is to prove them wrong.

What Pope Francis has called “the globalization of indifference” must be addressed. More than anything else, that is what was on my mind when I left Davos last week.

Lagarde


Google’s 3% UK Tax Rate?

David Cameron has defended the deal UK authorities have struck with Google over tax, saying the Conservatives have done more than any other government.

The PM told the Commons the tax “should have been collected under [the last] Labour government”.

Google agreed to pay £130m back in tax to HM Revenue and Customs – which said that was the “full tax due in law”.

But European MPs have described it as a “very bad deal”, and Labour said it amounted to a 3% tax rate.


The vice-chairwoman of a European tax committee said the deal showed the UK was preparing “to become a kind of tax haven to attract multinationals”.

French MEP Eva Joly said the settlement was “bad news for everybody”.

She said it was difficult to know on what basis the figure was reached and she criticised the attempt to “make publicity out of it” by talking about large-sounding figures which she said were a fraction of what should be paid.

Ms Joly, who is vice-chairwoman of the Special European Parliamentary Committee on Tax Rulings, said: “We will ask him [Mr Osborne] to come and explain and I hope he will.”

Mr Osborne has already faced criticism from some politicians in the UK over the tax deal. Shadow chancellor John McDonnell has written to him demanding details of how the settlement was reached.

And Conservative MP Mark Garnier, a member of the Treasury select committee, said the agreement represented a “relatively small” amount of money compared with Google’s UK profits.

Reports in Wednesday’s Times newspaper say Italy is poised to strike a far tougher tax deal with Google than the UK’s. It refers to stories in Italian media that suggest Google will pay £113m in back taxes to the Italian government, equating to a 15% tax rate.

The deal has not yet been completed so it is not known how many years it covers.

The Italian finance minister can also expect a call to appear before the MEPs, Ms Joly said.

Google is one of several multinational companies to have been accused of avoiding tax, in spite of making billions of pounds of sales in Britain.

Senior figures at the company said it would follow new rules which would see it pay more taxes in future.

Head of Google Europe Matt Brittin said last week: “We were applying the rules as they were and that was then and now we are going to be applying the new rules, which means we will be paying more tax.”

Google Tax

Is China’s Chief Economist Being Punished for Graft or Tough Statistics?

China’s top statistician was detained on Tuesday as part of a graft investigation, making him the latest senior economic official to fall from grace as the country battles economic and financial headwinds.

The Communist Party’s anti-graft watchdog made the dramatic announcement about National Bureau of Statistics chief Wang Baoan just as state radio aired comments Wang made earlier in the day at a press conference on the economy.

The sound bites were broadcast on state radio’s main daily news bulletin. But minutes later the news presenter read out a brief statement about the investigation into Wang. The apparently hasty arrangement is rare given the tight editorial and censorship procedures at top state media.

The Central Commission for Discipline Inspection said Wang was under investigation for “suspected serious violations of discipline”, a phrase that often refers to corruption. The CCDI’s statement was brief and did not suggest what the case might involve.

Wang, 52, was appointed as the bureau’s chief in April.

Before that, he spent 17 years in the finance ministry, joining in 1998 as a deputy director of its general office. He was later appointed head of the ministry’s policy planning office.

In 2007, Wang became head of the ministry’s economic construction office, which oversees the budget for state investment in infrastructure and is responsible for approving financial investment. One year later, Beijing announced a 4 trillion yuan stimulus package to revive the ailing economy amid the global financial crisis. The package involved a huge amount of government spending on infrastructure, must of which came under the jurisdiction of Wang’s office.

Wang left the economic construction office at the end of 2009, when he was appointed assistant financial minster.

In 2012, he was promoted to vice minister overseeing the offices of finance, social welfare. He was also the major promoter of the public-private partnership model of financing infrastructure projects.

Earlier on Tuesday, Wang gave a press briefing in Beijing, saying that the yuan had no ground to depreciate in the long term, and that international demand for the yuan was on the rise. He said the fluctuations in the stock market would only have a limited impact on the country’s economy, and he was confident about the market’s performance.

Last week, Wang also hosted a closely watched press conference held to release China’s gross domestic product figure for 2015, which hit a 25-year low of 6.9 per cent.

Wang is just the latest cadre with an extensive financial background to be investigated in Beijing’s massive anti-graft campaign. Yao Gang, vice-chairman of the China Securities Regulatory Commission, the country’s securities watchdog, was investigated in November. And Zhang Yujun, an assistant chairman overseeing brokerages and fund houses at the CSRC ,was probed in September.

Former statistics chief Qiu Xiaohua was jailed in 2007 for bigamy but made a comeback as an economics adviser for several state-owned enterprises after his release in 2008.

Business Travel

With the Cloud, Do We Still Have to Move Brains on Planes?

Ricardo Hausmann writes:  Think about it: You can call, email, and even watch your counterparty on FaceTime, Skype, or GoToMeeting. So why do companies fork out more than $1.2 trillion a year – a full 1.5% of the world’s GDP – for international business travel?

The expense is not only huge; it is also growing – at 6.5% per year, almost twice the rate of global economic growth and almost as fast as information and telecommunication services. Computing power has moved from our laptops and cellphones to the cloud, and we are all better off for it. So why do we need to move brains instead of letting those brains stay put and just sending them bytes? Why waste precious work time in the air, at security checks, and waiting for our luggage?

Before anyone starts slashing travel budgets, let’s try to understand why we need to move people rather than information.

More populous countries have more business travel in both directions, but the volume is less than proportional to their population: a country with 100% more population than another has only about 70% more business travel. This suggests that there are economies of scale in running businesses that favor large countries.

By contrast, a country with a per capita income that is 100% higher than another receives 130% more business travelers and sends 170% more people abroad. This means that business travel tends to grow more than proportionally with the level of development.

While businesspeople travel in order to trade or invest, more than half of international business travel seems to be related to the management of foreign subsidiaries.

But why do we need to move the brain, not just the bytes?  First, the brain has a capacity to absorb information, identify patterns, and solve problems without us being aware of how it does it. That is why we can, for example, infer other people’s goals and intentions from facial expressions, body language, intonation, and other subtle indicators that we gather unconsciously.

When we attend a meeting in person, we can listen to the body language, not just the spoken word, and we can choose where to look, not just the particular angle that the video screen shows. As a consequence, we are better able to evaluate, empathize, and bond in person than we can with today’s telecom technologies.

Second, the brain is designed to work in parallel with other brains. Many problem-solving tasks require parallel computing with brains that possess different software and information but that can coordinate their thoughts. That is why we have design teams, advisory boards, inter-agency taskforces, and other forms of group interaction.

Conference calls try to match this interaction, but it is hard to speak in turn or to see one another’s expressions when someone is talking. Conference calls have trouble replicating the intricacy of human conscious and unconscious group interactions that are critical to solve problems and accomplish tasks.

The countries that account for the most travel abroad, controlling for population, are all in Western Europe: Germany, Denmark, Belgium, Norway, and the Netherlands. Outside of Europe, the most travel-intensive countries are Canada, Israel, Singapore, and the United States, a reflection of the fact that they need to deploy many brains to make use of their diverse know-how.

Interestingly, countries in the developing world differ substantially in the amount of know-how they receive through business travel. For example, countries such as South Africa, Bulgaria, Morocco, and Mauritius receive much more know-how than countries at similar levels of development such as Peru, Colombia, Chile, Indonesia, or Sri Lanka.

The fact that firms incur the cost of business travel suggests that, for some key tasks, it is easier to move brains than it is to move the relevant information to the brains. Moreover, the fact that business travel is growing faster than the global economy suggests that output is becoming more intensive in know-how and that know-how is diffusing through brain mobility. And, finally, the huge diversity of business travel intensity suggests that some countries are deploying or demanding much more know-how than others.

Rather than celebrate their thrift, countries that are out of the business travel loop should be worried. They may be missing out on more than frequent flyer miles.

 Business Travel

Can the Welfare State Afford to Take in Immigrants?

Hans Werner-Sinn writes:  The armed conflict destabilizing some Arab countries has unleashed a huge wave of refugees headed for Europe. About 1.1 million came to Germany alone in 2015. At the same time, the adoption of the principle of freedom of movement within Europe has triggered massive, but largely unnoticed, intra-European migration flows. In 2014, Germany experienced an unprecedented net inflow of 304,000 people from other EU countries, and the number was probably similar in 2015.

Some EU members, including Austria, Hungary, Slovenia, Spain, France, and the initially welcoming Denmark and Sweden, have reacted by practically suspending the Schengen Agreement and reinstating border controls. Economists are not really surprised at this. In the 1990s, dozens of academic papers addressed the issue of migration into welfare states, discussing many of the problems that are now becoming apparent.

A fundamental issue is at stake. Welfare states are defined by the principle that those who enjoy above-average income pay more taxes and contributions than what they get back in the form of public services, while those with below-average earnings pay less than they receive. This redistribution, channeling net public resources toward lower-income households, is a sensible correction to the market economy, a kind of insurance against life’s vicissitudes and the rigors of scarcity pricing that characterize the market economy and have little to do with equitableness.

Welfare states are fundamentally incompatible with the free movement of people between countries if the newcomers have immediate and full access to public benefits in their host countries.  Only if migrants received only wages could efficient self-regulation in migration be expected.

British Prime Minister David Cameron drew the right conclusion from this: Welfare magnetism not only leads to an inefficient geographical distribution of people; it also erodes and damages the magnet. That’s why Cameron is demanding a limitation of the inclusion principle, even for intra-European economic migrants. Even if they find a job, says Cameron, migrants should get access to tax-financed welfare benefits only after four years.

The proposal does not necessarily imply hardship for EU migrants; it simply means that any support they may require over the four-year period is to be financed by their home country.

The home-country principle would usually be impossible to apply in these cases. But, for the same reasons outlined above, these migrants cannot be integrated by the hundreds of thousands into the welfare state without jeopardizing the system’s viability.

Therefore, the currently prevailing wage-replacement benefit system, which is applied when recipients do not work, should be replaced with a system offering wage supplements and community work. This would lower the benefits’ net costs and weaken incentives to migrate. Andrea Nahles, Germany’s labor minister, recently suggested as much, defending what Germans call the one-euro-jobs concept, which basically converts welfare into a wage.

That is sound advice in an otherwise chaotic state of affairs. If freedom of movement within Europe is to be maintained – and if high inflows of non-EU citizens continue – European welfare states face a stark choice: adjust or collapse.

Costly Immigrants

How to Measure China’s Slowdown

Stephen S. Roach writes:   The prospect of an economic meltdown in China has been sending tremors through global financial markets at the start of 2016. Yet such fears are overblown. While turmoil in Chinese equity and currency markets should not be taken lightly, the country continues to make encouraging headway on structural adjustments in its real economy.

Consistent with China’s long experience in central planning, it continues to excel at industrial reengineering. Trends in 2015 were a case in point: The 8.3% expansion in the services sector outstripped that of the once-dominant manufacturing and construction sectors, which together grew by just 6% last year.

This significant shift in China’s economic structure is vitally important to the country’s consumer-led rebalancing strategy. Services development underpins urban employment opportunities, a key building block of personal income generation. With Chinese services requiring about 30% more jobs per unit of output than manufacturing and construction, combined, the tertiary sector’s relative strength has played an important role in limiting unemployment and preventing social instability – long China’s greatest fear. On the contrary, even in the face of decelerating GDP growth, urban job creation hit 11 million in 2015, above the government’s target of ten million and a slight increase from 10.7 million in 2014.

The bad news is that China’s impressive headway on restructuring its real economy has been accompanied by significant setbacks for its financial agenda – namely, the bursting of an equity bubble, a poorly handled shift in currency policy, and an exodus of financial capital. These are hardly inconsequential developments – especially for a country that must eventually align its financial infrastructure with a market-based consumer society. In the end, China will never succeed if it does not bring its financial reforms into closer sync with its rebalancing strategy for the real economy.

Capital-market reforms – especially the development of more robust equity and bond markets to augment a long dominant bank-centric system of credit intermediation – are critical to this objective. Yet in the aftermath of the stock-market bubble, the equity-funding alternative is all but dead for the foreseeable future. For that reason alone, China’s recent financial-sector setbacks are especially disappointing.

But setbacks and crises are not the same thing. The good news is that China’s massive reservoir of foreign-exchange reserves provides it with an important buffer against a classic currency and liquidity crisis. To be sure, China’s reserves have fallen enormously – by $700 billion – in the last 19 months. Given China’s recent build-up of dollar-denominated liabilities, which the Bank for International Settlements currently places at around $1 trillion (for short- and long-term debt, combined), external vulnerability can hardly be ignored. But, at $3.3 trillion in December 2015, China’s reserves are still enough to cover more than four times its short-term external debt – well in excess of the widely accepted rule of thumb that a country should still be able to fund all of its short-term foreign liabilities in the event that it is unable to borrow in international markets.

Of course, this cushion would effectively vanish in six years if foreign reserves were to continue falling at the same $500 billion annual rate recorded in 2015. This was precisely the greatest fear during the Asian financial crisis of the late 1990s, when China was widely expected to follow other so-called East Asian miracle economies that had run out of reserves in the midst of a contagious attack on their currencies. But if it didn’t happen then, it certainly won’t happen now: China’s foreign-exchange reserves today are 23 times higher than the $140 billion held in 1997-98. Moreover, China continues to run a large current-account surplus, in contrast to the outsize external deficits that proved so problematic for other Asian economies in the late 1990s.

Still, fear persists that if capital flight were to intensify, China would ultimately be powerless to stop it. Nothing could be further from the truth. China’s institutional memory runs deep when it comes to crises and their consequences. That is especially the case concerning the experience of the late 1990s, when Chinese leaders saw firsthand how a run on reserves and a related currency collapse can wreak havoc on seemingly invincible economies. In fact, it was that realization, coupled with a steadfast fixation on stability, that prompted China to focus urgently on amassing the largest reservoir of foreign-exchange reserves in modern history. While the authorities have no desire to close the capital account after having taken several important steps to open it in recent years, they would most certainly rethink this position if capital flight were to become a more serious threat.

Yes, China has stumbled in the recent implementation of many of its financial reforms. The equity-market fiasco is especially glaring in this regard, as was the failure to clarify official intentions regarding the August 2015 shift in exchange-rate policy. These missteps should not be taken lightly – especially in light of China’s high-profile commitment to market-based reforms. But they are a far cry from the crisis that many believe is now at hand.

China's Slowdown