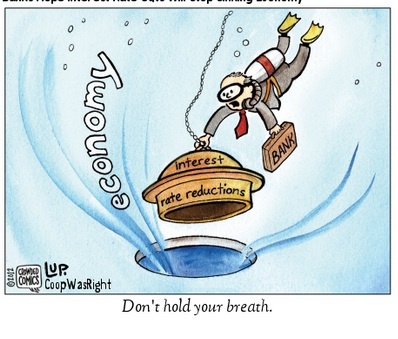
Taylor Begley writes;: A key regulatory response to the Global Crisis has involved higher risk-weighted capital requirements. This column documents systematic under-reporting of risk by banks that gets worse when the system is under stress. Thus banks’ self-reported levels of risk are least informative in states of the world when accurate risk measurement matters the most.
Following the Global Crisis, there has been a great deal of debate surrounding the risk-taking behaviour and incentives of large, global banks and their potential consequences for the stability of the financial system. Some argue that the privately optimal level of capital for a bank may differ substantially from the socially efficient capital level (see Admati et al. 2011, Thakor 2014). As policymakers consider new micro- and macro-prudential regulations to address these problems, it is important to understand the accuracy of self-reported risk measures generated by the internal models of large banks around the globe.
The measurement of bank risk is a key foundation for both micro-prudential and macro-prudential policy. Effective regulation relies on understanding the location and size of risks in the financial sector. In this column, we highlight a strong relationship between bank capitalisation and the risk reporting behaviour of banks under the current regulatory framework. Banks with low equity capital under-report their trading book risk, and do so more severely in times of system-wide financial stress. These results suggest that banks’ self-reported risk measures are least informative precisely during periods when accurate risk measurement is most important. Bank Risk
 SurveyMonkey chief executive officer Dave Goldberg died on May 1. Goldberg, who was 47 and had a reputation for being a nice guy in both an area and an industry where not everyone makes that effort.