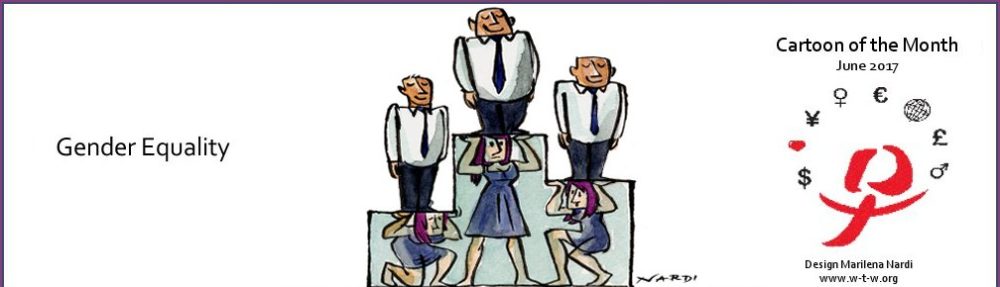
The Immeasurable Advantages of Being Rich

Lawrence Summers, Presidential Advisor, Harvard professor and President, remarks that it is not the the middle and lower classes resent what the wealthy have, but that they want more themselves.  How can this be achieved as we address the issue of inequaility.

Summers suggests that two important aspects of income inequality will not be effected by income redistribution: health care and education.

“Barry Bosworth and his colleagues at the Brookings Institution have examined changes in life expectancy starting at age 55 for the cohort of people born in 1920 and the cohort born in 1940. They found that the richest men gained roughly six years in life expectancy, middle-income earners gained roughly four years, and those in the lowest part of the distribution gained two years. To put this in perspective, the elimination or doubling of cancer mortality would mean less than a four-year change in life expectancy.”

Children of the affluent go to college more than others in part because they have 6000 hours of extra curricular activities that enhance their education.

In addressing the issues of inequality, Summers suggest that focus should be placed on the health and education of the lower 99% as well as the taxation of the 1%.

Education


Switzerland: Not Only Ice Cream, Chocolate and Baby Milk

Billions of transactions with our skinNestlé verjuengt sich mit Botox
Nestlé makes skincare deal with Canadian firm

Swiss giant Nestlé says it it is strengthening its hand on the specialized medical skin treatment market via a $1.4-billion cash deal with Canadian firm Valeant Pharmaceuticals International.

“With this deal we have acquired key strategic assets to extend Nestlé’s activities in the field of specialized, medical skin treatments,” the group’s chairman Peter Brabeck-Letmathe said in a statement issued on Wednesday.

The deal, worth about one billion euros, still needs a green light from regulators.

It would see Nestlé acquire the rights to commercialize several of Montreal-based Valeant’s key aesthetic dermatology products in the United States and Canada.

“The two markets together represent more than half of the fast-growing medical aesthetics market around the world,” Nestlé said in a statement.
Nestlé makes skincare deal with Canadian firm
Beauty Business
Autsch… knallharte Geschäfte mit Botox!

Australia Ranks Second for Women Entrepreneurs

Australian women at the Dell women in business conference in Austin were surprised by the news that Australia has the second best environments in the world for female entrepreneurs.

For the second year in a row, the Dell-sponsored Gender Global Entrepreneurship and Development Index showed Australia as ranking second only to the US in terms of “the conditions that foster high potential female entrepreneurship”.

In both years Australia ranked a very clear second ahead of many other developed countries — and streets ahead of any developing countries — as a place for women to start their own companies.

This year, the survey has been expanded from an initial 17 countries to 30. On closer analysis there are a number of elements to the story.

The survey itself takes into ­account many objective factors from organisations such as the World Bank and the International Labour Organisation comparing countries. Australia ranks with the US, Sweden and France in support for small and medium enterprises. It scores high in other criteria such as access to childcare, the freedom to do business, and access to technology.

Australia also ranks high in equal rights and educational levels for women.

The lesson from this is that, at least compared to the position of women in many other countries, Australia has a lot better preconditions for women in business than we like to think.

In the survey the US scored 83 as a place for female entrepreneurs. Australia scored 80, followed by Sweden at 73. This puts us well ahead of France and Germany at 67, Chile at 55 and Britain at 54, with others else below this.

As one of the survey’s researchers pointed out, a stunning 73 per cent of the countries scored poorly — less than 50 or below out of 100.

So it does make the point that Australians do need to take a look around at their country in a global context, and while it might not be as great as would like it to be, the basic framework of the country for would-be female entrepreneurs is a lot better than in many other countries.

If the survey is right, as Australian entrepreneur Wendy Simpson points out, maybe it is time for more women to take the jump to start their own businesses.

Of course, saying that Australia ranks a lot higher than India (26), Uganda and Egypt (19), Bangladesh (17) and Pakistan (11) as a place to do business is no reason for complacency.

But all that said, is there an “x” factor in Australia — maybe cultural — that is holding back women in business at all levels?

There are similar issues facing women in business and women thinking about founding their own business around the world.

As Dell’s entrepreneur in residence, Ingrid Vanderveldt, said yesterday, the biggest single thing preventing women from starting their own businesses (at least in the developed world) is lack of confidence.

Do Australian women lack confidence or are there cultural ­elements in Australia that hold women back or lead women to hold themselves back in business in general?

Maybe the real question is not why Australia happens to rank second in this survey but what can we learn from top-ranking US to improve things.

The US business culture is based on people who know they have to fight hard to compete with 300 million others. Not a lot of room for any Australian-style self-deprecation or hiding a light under a bushel.  This difference is even more pronounced in the attitudes to business and personal success by women in both countries.  (Glenda Korporall)

Don't Hide Your Light Under a Bushel

Empires of Any Sort Are Not for the 21st Century

John Yemma writes in the Christian Science Monitor:  Empires solve a multitude of problems. They lay a blanket of authority over rival peoples and belief systems. They institute common standards and languages and clear the way for trade and travel across vast geographies. The early 20th century was a world of empires – Habsburgs in middle Europe, Romanovs across Eurasia, Ottomans in the Middle East. Britain, France, Portugal, and Belgium had carved up Africa and Asia. Even the United States was in the empire business, managing territories it wrested from Spain at the turn of the century (the Philippines, Cuba, and Puerto Rico) and indirectly managing Latin America through influence and intervention.

Pax Imperialis was at its height in 1910. In “The Guns of August,” historian Barbara Tuchman describes the funeral that year of Edward VII of England, which was attended by nine kings riding three by three and adorned “with plumed helmets, gold braid, crimson sashes, and jeweled orders flashing in the sun.” Seventy nations were gathered in a show of order and honor. But “on history’s clock,” she wrote, “it was sunset, and the sun of the old world was setting in a dying blaze of splendor never to be seen again.”

Historian Gerard DeGroot describes the Great War that those sovereigns and their generals blundered into four years later – 100 years ago this August – the shattered empires left behind, and the many ways we are still sorting through the wreckage. Take a subject in the news today: Ukraine. Internal differences of language, religion, and affinity can be traced to the empires that overlaid its territory before World War I. Hryhoriy Nemyria, a former deputy prime minister of Ukraine, describes his country as still dealing with having been “the periphery of peripheries of three powers” – Russia, and the Ottoman and Austro-Hungarian empires.

The Europe of the 21st century may seem fixed and settled, its frontiers barely noticeable. But that is a recent phenomenon. The farther east Europe goes, the less remains settled, the more “borders and people don’t match,” notes Dan Hamilton, a specialist on transatlantic relations at Johns Hopkins University. That mismatch is true in much of Africa, the Middle East, and Asia.

One hundred years is not much time to rebuild from the great political earthquake of 1914, especially with the aftershocks that followed. In many ways, 2014 is a year in which history has insisted it be reviewed, if for no other reason than the coincidence of significant anniversaries. Seventy-five years ago, Hitler invaded Poland, touching off World War II. Seventy years ago was D-Day, which President Obama, amid the new challenges posed by Russian President Vladimir Putin, will mark next month in a speech likely to signal continued American support for a “Europe whole and free.” Those words, by the way, come from a speech by former President George H.W. Bush – exactly 25 years ago – just months before the Berlin Wall fell.

From the vantage of 2014, the age of empire is a distant memory of plumed hats and crimson sashes. Also from this vantage, the age of mental empires based on ideology or religion is, if not fully over, at least approaching sunset. What we must not allow is economic or nationalistic empires to take their place.

The terrible destruction and lost lives of two great wars and a dozen other 20th-century conflicts can be redeemed by a 21st century in which the varied peoples of Earth voluntarily, thoughtfully, peacefully, and modestly govern themselves.

Empires


Italian Government Commits to Women Entrepreneurs

A Memorandum of Understanding was signed by Equal Opportunities, Ministry of Development and businesses.  Banks acceding to the new Protocol will indicate the financial ceiling that can be used for the granting of loans related to specific lines of action: new investments for the development of the business or profession; creation of new businesses or start-up of the profession.  After Italy’s financial difficulties this is good news.   Loans are provided on competitive terms compared to the normal supply of credit and similar transactions with the same degree of risk. Benefiting from the guarantee of the special section of the Department of Equal Opportunities Fund, the cost of financing could be further lowered.

The President of Cna, the National Confederation for the Craft Sector and Small and Medium Enterprise of Italy, said, “We appreciate both the Government’s commitment both by the Italian Banking: is the recognition of the role that women entrepreneurs can play in the revitalization of our country. ”

“This Protocol ‘Health concludes” it is a great opportunity to make a qualitative leap in relations between banks and firms. But a signature is not enough. Now we need all of them that the parties commit themselves to transform into action the principles set out in the plan. And, to avoid that the Protocol will remain on paper, the CNA will promote a comprehensive information activities aimed at entrepreneurs and the banks themselves. ”

Pink Ladies in Italy

The Role of Household Debt in Financial Crises

Did the response to the financial crisis focus too much on banks while neglecting over-indebted homeowners?  House of Debt: How They (and You) Caused the Great Recession, and How We Can Prevent It from Happening Again, by Atif Mian and Amir Sufi, University of Chicago Press.

House of Debt focuses on the deterioration of household balance sheets, an analysis that has profound implications for policy directed both at preventing crises and responding to them when prevention fails.

The book examines a profoundly important question: what causes protracted downturns in economic activity? They have marshalled new data – for example, on spending by zip code – to test their hypotheses, assembling such a range of evidence from so many different sources that their conclusions are not susceptible to challenge by those looking to point out statistical errors.

Most in the financial community, the policy community and the commentariat see a breakdown in financial intermediation as the root cause of the financial crisis and Great Recession. The failure to bail out Lehman Brothers is usually viewed as the prelude to

The authors argue that, rather than failing banks, the key culprits in the financial crisis were overly indebted households. They highlight how harsh leverage and debt can be – for example, when the price of a house purchased with a 10 per cent downpayment goes down by 10 per cent, all of the owner’s equity is lost. They demonstrate powerfully that spending fell much more in parts of the country where house prices fell fastest and where the most mortgage debt was attached to homes. So their story of the crisis blames excessive mortgage lending, which first inflated bubbles in the housing market and then left households with unmanageable debt burdens. These burdens in turn led to spending reductions and created an adverse economic and financial spiral that ultimately led financial institutions to the brink.

Households do not spend while they are still overly indebted, which precipitates slow growth even after banking is restored to health. Spending slowdowns are caused by household over-indebtedness, so of course they precede problems in the banking system. And, when consumers do not spend, businesses have less need to borrow to finance investment, inventories or receivables.
Their analysis, presented with far more depth and subtlety than I have been able to reflect here, is a major contribution that furthers our understanding of the crisis. It certainly affects what I will examine in trying to predict and forestall future crises. And it should influence policies aimed at crisis prevention by demonstrating the insufficiency of keeping financial institutions healthy and by making a case for macroprudential measures directed at preventing runaway growth in household debt.

With hindsight some argue that more pain should have been imposed on the financial sector. In the moment, though, the overwhelming imperative was restoring confidence at a time when complete breakdown looked like a real possibility. The government got back substantially more money than it invested. All of the senior executives who created these big messes were out of their jobs within a year. And stockholders lost 90 per cent or more of their investments in all the institutions that required special treatment by the government.

Reducing mortgage debt would have spurred spending.  The idea of  “cram-down”: the notion that bankruptcy judges should be allowed to write down mortgage debt, and that permitting them to do so would increase the bargaining power of homeowners seeking relief probably would have worked.

Critics who disagree at this late date are obliged to provide an alternative analysis of the political calculus, not a mere recitation of the arguments for cram-down.  In the US at the time of the crisis there was no political will to do “cram-down.”

Banks had substantial mortgage holdings and especially large quantities of subordinated second mortgages and home equity lines of credit, which would have been wiped out if mortgage principal had been reduced in a way that respected the seniority of first mortgages. We recognised that large-scale principal reduction would draw in a large number of mortgages that were not delinquent and would otherwise be paid in full. As a consequence, there was the risk of sucking hundreds of billions of dollars out of the banking system. Given that government funds for capital infusions were scarce and that each dollar of bank capital supports $12 of lending, we worried that the spending gains from reducing mortgage debt might well be exceeded by the spending losses from reducing the flow of capital. This fear may have been exaggerated. If they think so, Mian and Sufi owe an explanation as to why.

Future lending might have been chilled. The housing market’s problems might have been prolonged.  If the government had bought underwater mortgages from banks.
There was the danger of prolonging the housing market’s problems. Even the relatively limited programmes in place have spent as much as a third of their money delaying, rather than avoiding, foreclosures. All that we heard at the time suggested that a significant part of the reason why the housing market was dead was that no one wanted to buy because of a fear that it had further to fall. Delaying inevitable foreclosures with relief risked exacerbating this problem and risked larger foreclosure discounts when houses were ultimately sold.

In many cases mortgage assets were carried on banks’ books at valuations far above what appeared to be current market value. Buying them at such valuations would have been a massive backdoor subsidy to banks of the kind we would not accept.  All future work on financial crises will have to reckon with the household balance sheet effects the authors stress.

Underwater Mortgages

UAE Favored Destination for Migrating Professionals

The UAE has emerged as the most popular destination for professionals looking to migrate, according to a new study by networking site LinkedIn.  The global study, which tracked talent migration among the 300 million members on LinkedIn’s network, found that the UAE gained 1.3 per cent as a percentage of its total workforce in a 12-month period, topping a list of 20 nations.

Of this talent inflow, 75 per cent was from outside the Middle East, and more than 40 per cent reported a new role with a promotion and higher designation, a statement said.  India was the top destination from where most professionals moved to the UAE, followed by the UK, Pakistan, the United States and Saudi Arabia.

The industry sectors that attracted the most talent were management & leadership, engineering, sales accounting and lifestyle.

The UAE has attracted more professional talent as a percentage of its workforce than countries such as Canada, Brazil, Switzerland, Saudi Arabia, South Africa, India, Singapore and Australia, the statement said.

Ali Matar, head of Talent Solutions, LinkedIn MENA, said: “This latest study shows that two Middle Eastern nations, UAE and Saudi Arabia, have gained talent at 1.3 per cent and 0.9 per cent respectively. Talent inflows are from Europe, USA, the Subcontinent, and other Arab nations, showing that the Gulf states still retain their attractiveness for employment.”

Overall, the study found that the countries that topped the list in exporting talent to other countries were Spain, United Kingdom, France, the United States, Italy and Ireland.

The UAE is building up its talent base as it prepares to host Expo 2020 in Dubai. The six-month long event is expected to provide up to 277,000 new job opportunities in the market and boost the economy.  W-T-W.org will explore the reasons why and particularly opportunities for women.

UAE


Push Is On for More Female Financial Planners

Just 23 percent of financial planners are women, a number that inspired a trade group to campaign for more women to the field.

Ever since Manisha Thakor, the founder of MoneyZen Wealth Management, entered the financial services field, she’s been one of the few women at the table. “In my early 20s, I tried to behave like the other people around me by wearing dark suits, being serious and showing no sign of feminine energy, but eventually the real me broke through,” she says.

As her real self, which Thakor describes as “authentically quirky,” she has found her greatest success: Now in her mid-40s, she runs a thriving business helping clients –- who are mostly women –- manage their money, and she is also a popular author, speaker and expert on personal finance issues. She attributes her ability to get ahead in a male-dominated field to her early financial education: Her father taught her about investing when she was 11. She was fascinated and went on to pursue an investment banking career and then an MBA at Harvard University.
Push Is On for More Female Financial Planners

Baldwin, Mike

Baldwin, Mike

Fixing Banks is Not the Answer?

Adair Turner writes about addresses the Eurozone’s economic problems:

A “credit crunch” – particularly in trade finance – was certainly a key reason why the financial crisis generated a real economy recession. Taxpayer-funded bank rescues, higher bank capital requirements, and ultra-easy monetary policy have all been vital to overcome credit supply constraints. But there is strong evidence that once the immediate crisis was over, lack of demand for credit played a far larger role than restricted supply in impeding economic growth.   Draghi’s Funding for Lending Scheme
That argument is persuasively made by Atif Mian and Amir Sufi in House of Debt, an important new book that analyzes US data on a county-by-county basis. Mian and Sufi show that the recession was caused by a collapse of household consumption, and that consumption fell most in those counties where pre-crisis borrowing and post-crisis real-estate prices left households facing the largest relative losses in net wealth.

Draghi