No Shortcuts to European Recovery?

There is a growing consensus that austerity is contributing to the Eurozone’s macroeconomic malaise, but also that spending cuts are needed in the long run to achieve fiscal sustainability. Some commentators have advocated a temporary tax cut financed by unsterilised ECB purchases of long-term public debt, accompanied by a commitment to future spending cuts. This article argues that such commitments are simply not credible – especially given the moral hazard problem created by central bank monetisation of debts. No Shortcuts to European Recovery

No Shortcuts?


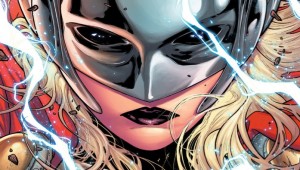
Pop Culture Brings in Female Heroes

Marvel’s Thor, a woman, debuts on newstands.  She joins a growing list of superhuman heroines leading their own comic books — Captain Marvel, Batgirl and Catwoman, among others — as Marvel and DC push to diversify and improve the representation of women on their pages.

Part of this improvement comes through in the way these characters are dressed. Instead of a tight black bathing suit, Captain Marvel now wears a red, blue and yellow jumpsuit that evokes her Air Force roots. Over in Gotham, Batgirl has ditched the tight spandex and bright yellow heels for a leather motorcycle jacket, a detachable cape and Doc Martens.

Genevieve Valentine, lead writer on Catwoman, says having a Catwoman who wears heels in her daily life but not when she’s fighting “seems like a small thing, but of course, it’s not. It’s sort of an institutional recognition of an audience that’s always been there.”

Jeanine Schaefer, Marvel’s senior manager for talent acquisition, says they are “aware that we don’t have as many women working for us as we have men.”  The issue of diversity is one that Marvel executives are seriously considering, but the change is going to take some time, she adds. “Mentoring women when they come in the door, making sure we’re placing them where they can flourish.”

Before they can hire these women, editors and talent scouts like Schaefer have to find them. And that’s where Janelle Asselin comes in.  “A lot of the female creators that are up and coming are unknown quantities,” she says. “It can be hard to know how they will work on a monthly schedule. But editors need to take more risks and give more female creators a chance.”

To make it easier, Asselin started Hire This Woman. In it, she highlights female comics professionals and includes a brief interview about how fast they work, their ideal professional environments — information editors might need or want to know when hiring someone.

Her feature, and the others like it, are all part of a broader conversation happening all over the internet, on platforms like Twitter and Tumblr.

“There’s a growing and outspoken contingent of female fans that are fed up with being treated as not important,” Asselin says.

The harassment doesn’t always stay on the Internet. Asselin’s bank accounts were compromised after her article was published online, and independent comics editor Caitlin Rosberg says, “some people have had stuff mailed to their homes as a threat of ‘I know where you live.’ ”

Marvel’s Jeanine Schaefer believes this behavior is partly driven by extreme fear on the part of some comics fans.

“There’s this perception that, ‘Well, if we let women in, then everything is going to change. They’re going to take away everything that I like about comics,'” Schaefer says.

And Schaefer hopes that bringing more women and diverse voices into the creative process will prove to those fans that their favorite stories will only be enhanced by the different perspectives.

Asselin says the level of vitriol some fans aim at women working in or commenting on the comics industry is “not an OK way to treat people,” no matter the reason, but she thinks it can and will get better. These fans just need to accept that women aren’t going to leave the comics world.

After all, a genre where the unlikeliest of misfits can be heroes should have the best variety of voices to tell those stories.
Super Woman

Abigail Johnson to CEO at Fidelity

Abigail Johnson takes the helm at FIdelity.  She succeeds her father.  Her grandfather founded the company after the Second World War.  Ms. Johnson started at Fiedlety almost two decades ago as an asset analyst and portfolio manager.  She is known more for her perational skills in putting her father’s ideas into place.

While she is sometimes critisized for being too private and introverted, she knows every nook and cranny of Fidelity.  According to Morningstar, they have lost 9 billion in assets since September.  The question is how they willl do witth the current craze for Exchange Traded FUnds.  Abigail Johnson got the CEO jjob which few women have been able to achieve.

Woman to Manage Assets


Can Service Industries Replace Manufacturing?

Can Services Replace Manufacturers as the drivers of the economy?  Dani Rodrik writes: The global discussion about growth in the developing world has taken a sharp turn recently. The hype and excitement of recent years over the prospect of rapid catch-up with the advanced economies have evaporated. Few serious analysts still believe that the spectacular economic convergence experienced by Asian countries, and less spectacularly by most Latin American and African countries, will be sustained in the decades ahead. The low interest rates, high commodity prices, rapid globalization, and post-Cold War stability that underpinned this extraordinary period are unlikely to persist.

A second realization has sunk in: Developing countries need a new growth model. The problem is not just that they need to wean themselves from their reliance on fickle capital inflows and commodity booms, which have often left them vulnerable to shocks and prone to crises. More important, export-oriented industrialization, history’s most certain path to riches, may have run its course.

Ever since the Industrial Revolution, manufacturing has been the key to rapid economic growth. China, which has emerged as the archetype of this growth strategy since the 1970s, traveled a well-worn path: industrial manufacturing.

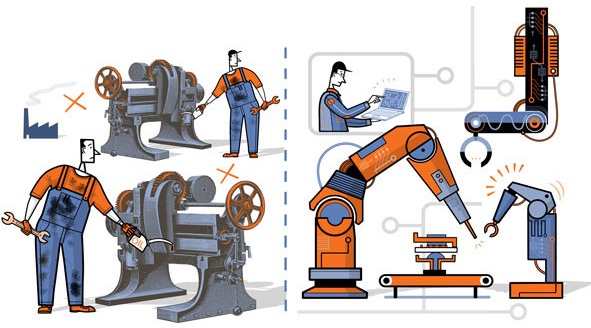
But manufacturing today is not what it used to be. It has become much more capital- and skill-intensive, with greatly diminished potential to absorb large amounts of labor from the countryside.

While global supply chains have facilitated entry into manufacturing, they have also reduced the gains in terms of value added that accrue at home. Many traditional industries, such as textiles and steel, are likely to face shrinking global markets and over-capacity, driven by demand shifts and environmental concerns. And one downside of China’s success is that many other countries are finding it much harder to establish more than a niche in manufacturing.

Can service industries play the role that manufacturing did in the past?

Among the optimists are Ejaz Ghani and Stephen D. O’Connell of the World Bank argue that service industries could serve as a growth escalator, the role traditionally assumed by manufacturing.

In particular, they show that services have exhibited “unconditional convergence” in productivity recently. That is, countries furthest away from the global frontier of labor productivity have seen the fastest productivity growth in services.

This would be very good news, but there are reasons to be wary. The Ghani-O’Connell evidence includes data starting in the early 1990s, during which developing countries were experiencing economy-wide convergence, boosted by capital inflows and commodity windfalls. It is unclear whether their conclusions extend to other periods.

Two things make services different from manufacturing. First, while some segments of services are tradable and are becoming more important in global commerce, these typically are highly skill-intensive sectors that employ comparatively few ordinary workers.

Banking, finance, insurance, and other business services, along with information and communications technology (ICT), are all high-productivity activities that pay high wages. They could act as growth escalators in economies where the work force is adequately trained. But developing economies typically have predominantly low-skilled labor forces. In such economies, tradable services cannot absorb more than a fraction of the labor supply.

That is why, for all of its success, the ICT sector in India has not been a primary driver of economic growth. By contrast, traditional manufacturing could offer a large number of jobs to workers straight off the farm, at productivity levels three to four times that in agriculture.

In today’s developing countries, the bulk of excess labor is absorbed in non-tradable services operating at very low levels of productivity, in activities such as retail trade and housework. In principle, many of these activities could benefit from better technologies, improved organization, and greater formalization. But here the second difference between services and manufacturing comes into play.

Partial productivity gains in non-tradable activities are ultimately self-limiting, because individual service activities cannot expand without turning their terms of trade against themselves. By contrast, in services, where market size is limited by domestic demand, continued success requires complementary and simultaneous gains in productivity in the rest of the economy.

So I remain skeptical that a services-led model can deliver rapid growth and good jobs in the way that manufacturing once did. Even if the technological optimists are right, it is difficult to see how that will enable developing countries to sustain the kind of growth they experienced over the last couple of decades.

Manufacturing

Tirole, Who Argues for Regulation of Big Businesses, Wins Nobel

A French researcher whose life’s work has been devoted to regulating large companies has won the Nobel Prize for Economics. Jean Tirole, scientific director of industrial economics at Toulouse University, was named the 2014 winner of the Economics Nobel prize on Monday “for his analysis of market power and regulation.’

A mathematician by training, Tirole’s work focuses heavily on game theory and information theory, which focuses on how people use strategic information. His research is focused on the problems that regulators often face when taming oligopolies. Tirole, 61, has advocated for tailored approaches in favor of blunt regulations such as price caps. In 2013, he contributed to a report that called to “complete the euro” with deeper European integration. His research on “Intrinsic and Extrinsic Motivation” challenges the notion that individuals always respond to incentives. Triole has shown that the best regulation should carefully be adapted to each specific industry.

“His analysis of firms with market power provides a unified theory with a strong bearing on central policy questions: how should the government deal with mergers or cartels, and how should it regulate monopolies?” the academy said. “Tirole showed theoretically that such rules may work well in certain conditions, but do more harm than good in others. Price caps can provide dominant firms with strong motives to reduce costs — a good thing for society — but may also permit excessive profits — a bad thing for society. Cooperation on price setting within a market is usually harmful, but cooperation regarding patent pools can benefit everyone. The merger of a firm and its supplier may encourage innovation, but may also distort competition.”    Intrinsic and Extrinsic Motivation

Regulation


Shareholder Activism in US

Shareholder Activisim  Darden Restaurants,  owner of the Olive Garden, lost a more than nine-month battle against Starboard Value LP, which persuaded investors to replace the company’s entire board at its shareholder meeting today.

Investors voted for the 12 directors at Darden’s annual meeting in Orlando, Florida, where the company is based.Starboard’s victory followed a carefully orchestrated campaign against Darden that included an almost 300-page list of recommendations for improving the business. Starboard criticized the company for selling off the Red Lobster chain and lobbied instead for Darden to separate its real-estate assets. The investment firm also knocked Olive Garden for giving out too many breadsticks to customers and not selling enough wine.

Starboard has been pushing for changes at Darden since December. Barington Capital Group LP, another activist shareholder, had also lobbied Darden to consider other options to boost value.

Starboard announced the board slate in May, saying Darden’s management had shown “contempt for shareholder interests.” The directors voted in today include the former CEO of Office Depot Inc.;the CEO of Checkers Drive-In Restaurants Inc.; and  the chairman and CEO of Smith & Wollensky Restaurant Group Inc.

Today’s result is “extraordinary” because shareholders typically shy away from replacing an entire board over concerns about continuity.

“Following the Red Lobster sale they seem to have lost touch with their investors,” Elson said in an interview. “You shouldn’t get to this point. Obviously the dissatisfaction level was so significant.”

 Red Lobster Running

China’s Slowdown May be Good

Kenneth Rogoff writes:  While virtually every country in the world is trying to boost growth, China’s government is trying to slow it down to a sustainable level. As China shifts to a more domestic-demand driven, services-oriented economy, a transition to slower trend growth is both inevitable and desirable. But the challenges are immense, and no one should take a soft landing for granted.

As China’s economy grows relative to the economies of its trading partners, the efficacy of its export-led growth model must inevitably fade. As a corollary, the returns on massive infrastructure investment, much of which is directed toward supporting export growth, must also fade.

Consumption and quality of life need to rise, even as China’s air pollution and water shortages become more acute in many areas. But, in an economy where debt has exploded to more than 200% of GDP, it is not easy to rein in growth gradually without triggering widespread failure of ambitious investment projects. Even in China, where the government has deep pockets to cushion the fall, one Lehman Brothers-size bankruptcy could lead to a major panic.

Think of how hard it is to engineer a soft landing in market-based economies. Where is China’s economy now? Most evidence suggests that the economy has slowed significantly. One striking fact is that annual growth in electricity demand has fallen sharply, to below 4% for the first eight months of 2014, a level recorded previously only in the depths of the global financial crisis that erupted in 2008. For most of China’s modernization drive, electricity consumption has grown faster than output, not slower.

Weakening electricity demand has tipped China’s coal industry into severe distress, with many mines effectively bankrupt.  Exports have also slowed, given sluggish growth in the rest of the world. Commodity exporters such as Australia, Indonesia, and Brazil have already felt the effects of slowing Chinese growth, as have countries, such as Germany and Switzerland, that depend on satisfying China’s voracious demand for capital-intensive goods.

Can China’s government engineer a soft landing while weeding out corruption, reducing pollution, and liberalizing markets to ensure long-term growth?

China’s growth rate remains perched at a very high level, so there is a great deal of room to fall. The potential vulnerability of Western exports and equity prices is massive. Of the two major instances of policy tightening occurring in the world today, the US Fed’s may be the easier one to understand, but it is not necessarily more consequential for the world than what is happening in China.

Soft Landing?

Interest Rates Impacts Different Economies Differently

Daniel Gros writes: Within the eurozone, where until recently external accounts were nearly balanced, a similar creditor/debtor spectrum has emerged, with Germany and the Netherlands at one end, and much of the eurozone south at the other. This partly explains both the hostile stance toward QE adopted in the German financial press and the over-indebted periphery countries’ increasingly desperate calls for more action by the ECB.

In the eurozone, however, QE is a questionable response to such calls. QE is a special instrument used when a central bank’s short- and medium-term policy rates are already at zero and it wants to lower long-term interest rates. This implies that QE can be effective only in economies in which changes in long-term (market) interest rates play an important role in the private sector.

But this is not the case in Europe, where most investment is financed via bank loans that typically do not have long-term maturities – often less than five years – because banks themselves have little secure long-term financing. Moreover, the interests rates charged on these loans are not linked to market rates, but rather to the bank’s refinancing cost, which is already close to zero     Credit and Debt

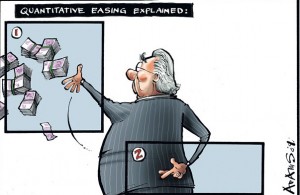
Quantitative Easing

Big Impact of Tiny Qatar

Brahma Chelaney writes:  Qatar may be tiny, but it is having a major impact across the Arab world. By propping up violent jihadists in the Middle East, North Africa, and beyond, while supporting the United States in its fight against them, this gas-rich speck of a country – the world’s wealthiest in per capita terms – has transformed itself from a regional gadfly into an international rogue elephant.

Using its vast resources, and driven by unbridled ambition, Qatar has emerged as a hub for radical Islamist movements. The massive, chandeliered Grand Mosque in Doha – Qatar’s opulent capital – is a rallying point for militants heading to wage jihad in places as diverse as Yemen, Tunisia, and Syria. As a result, Qatar now rivals Saudi Arabia – another Wahhabi state with enormous resource wealth – in exporting Islamist extremism.    Qatar’s Impact

Women Drive in Qatar

Bankruptcy in Large USFinancial Institutions

The Jeffrey M. Lacker of the Federal Reserve of Richmond reports;  Here are the highlights of my speach at the National Conference of Bankruptcy Judges Annual Meeting at Chicago, Ill.

  • The bankruptcy process is an effective tool for reconciling the incentives of creditors and debtors. Yet the government has a long history of handling large complex financial institutions outside the Bankruptcy Code.
  • This has created two mutually reinforcing conditions: Investors feel protected by an implicit commitment of government support, and policymakers feel compelled to provide that support to avoid a disruptive adjustment of expectations.   Jeffrey Lacker’s Speech

Bankruptcy